The Closing Itself
What Still Has to Reach the Title Company on a Florida For-Sale-by-Owner Sale?
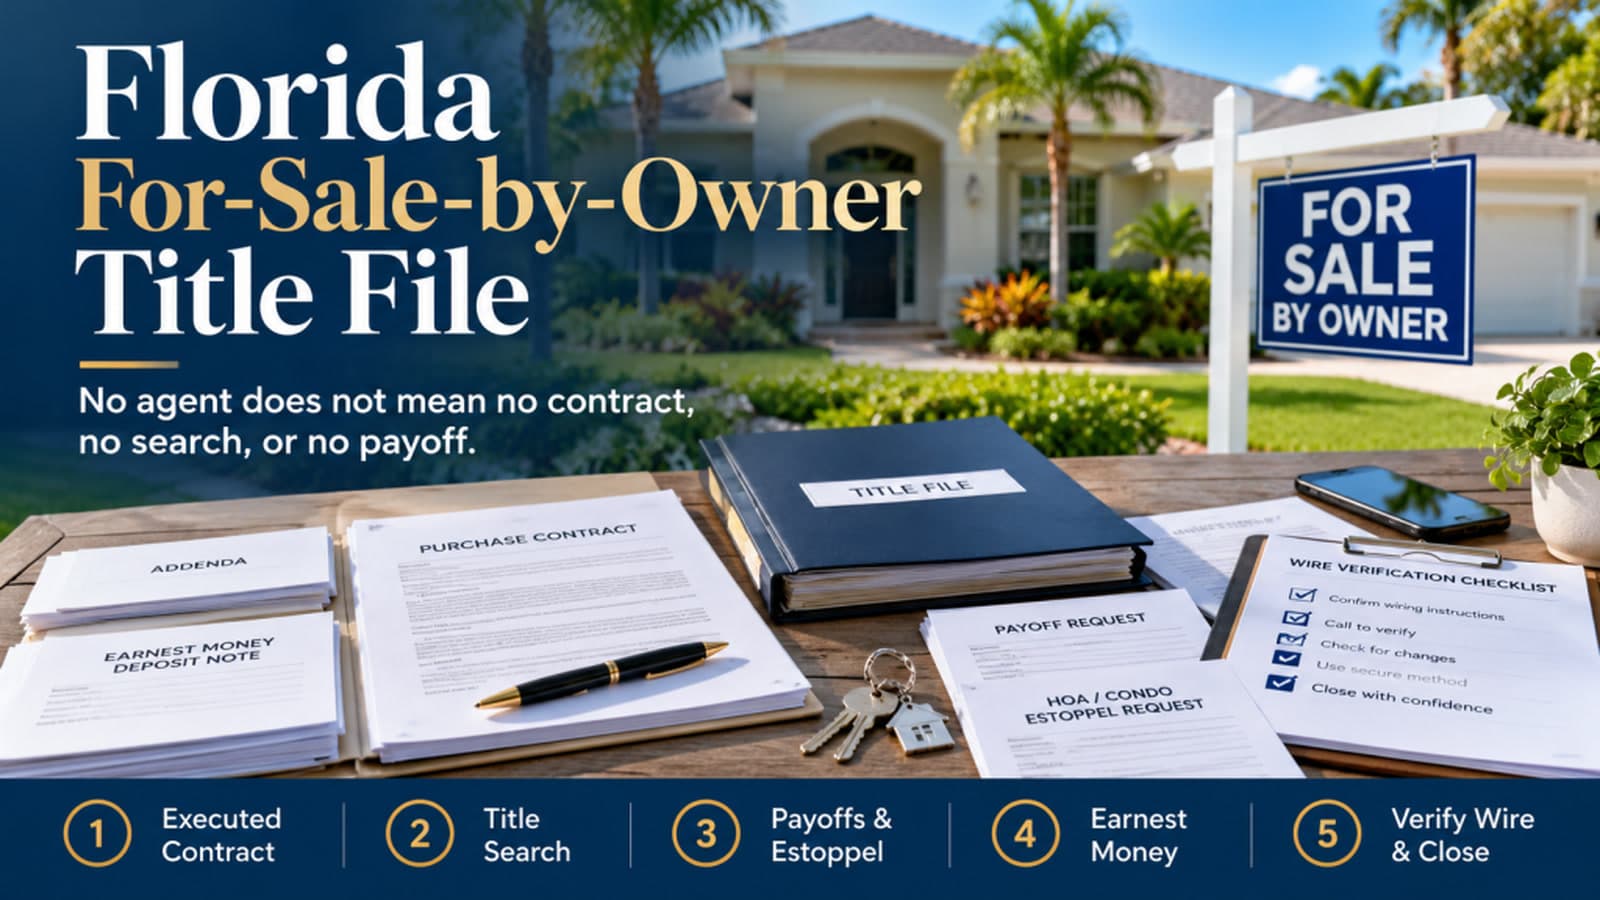
A for-sale-by-owner sale still needs the same title file. The file opens from the executed contract, not from a text that the parties agreed.
Straight answers on title insurance, closing timelines, and Florida settlement so buyers, sellers, and real estate professionals can close with fewer surprises.

The Closing Itself
A for-sale-by-owner sale still needs the same title file. The file opens from the executed contract, not from a text that the parties agreed.

The Closing Itself
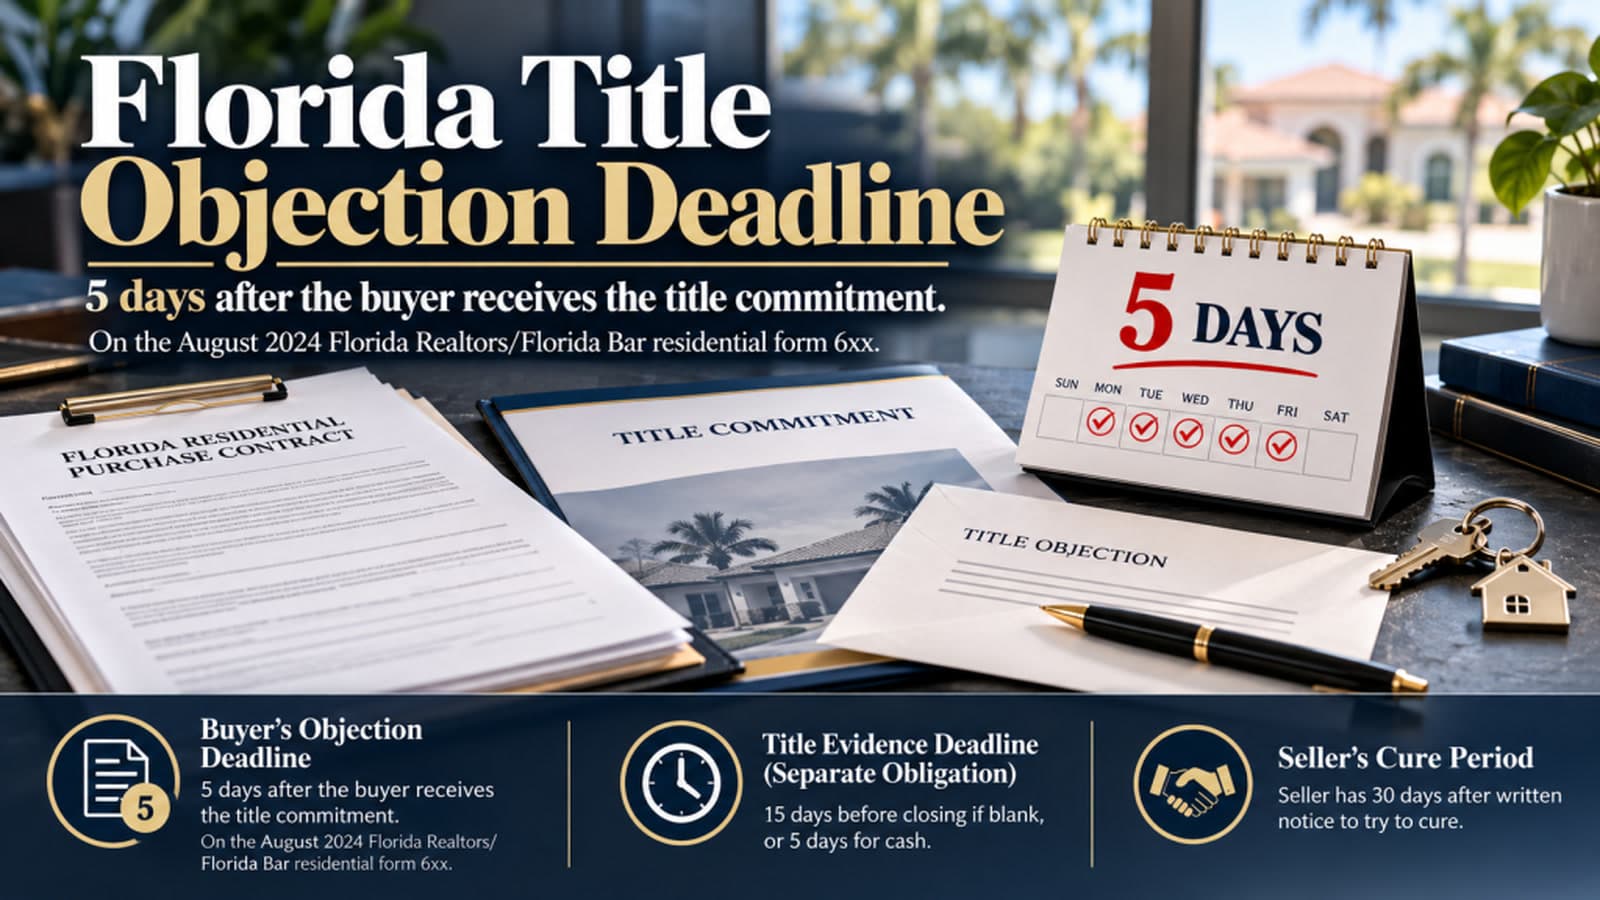
The title objection deadline is the written notice after the commitment. A missed notice can waive the objection. It does not clear a lien.

Title Insurance
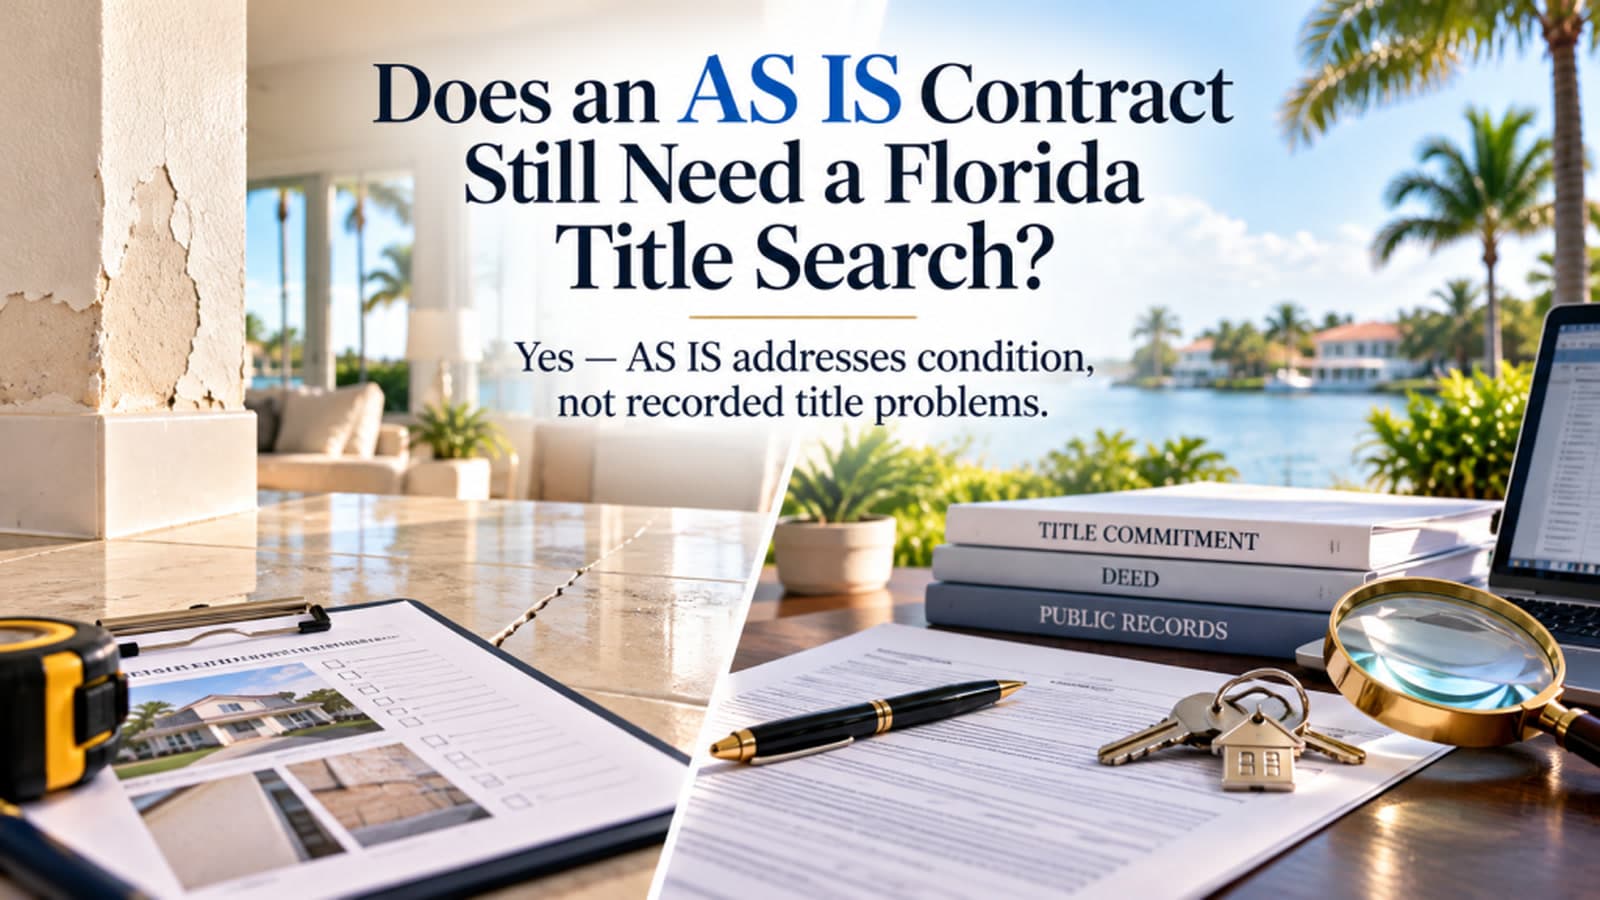
AS IS covers the house's condition and the seller's repair duty. The title search still has to read the record.

The Closing Itself
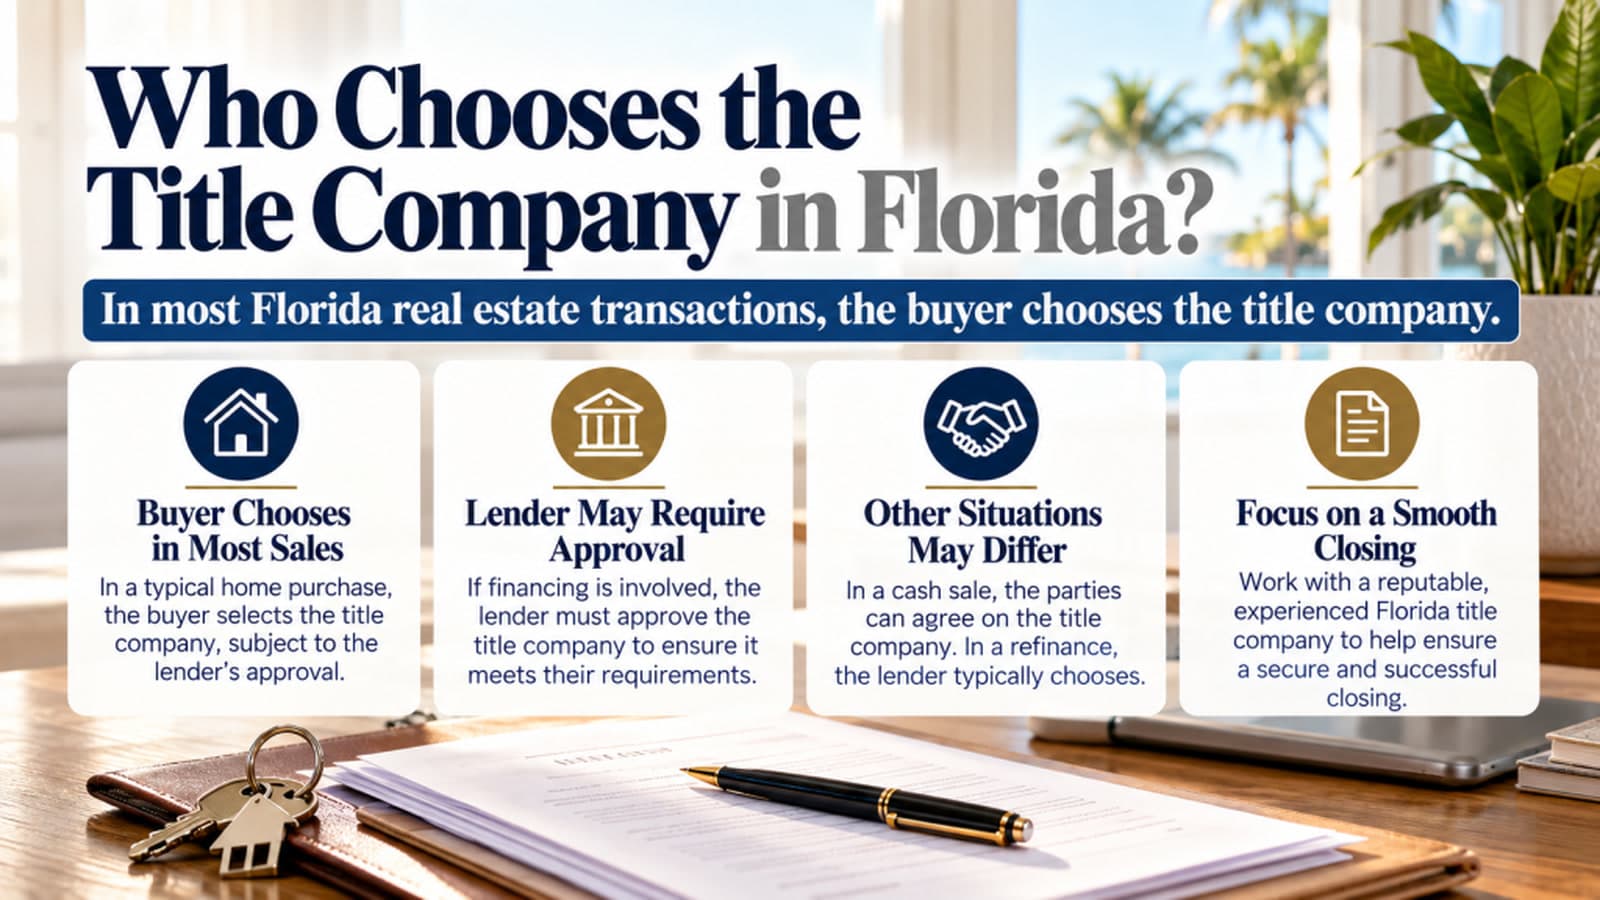
The contract names the title company and the settlement agent. A blank line is not a choice. On a federally related mortgage, the seller cannot require one company.

The Closing Itself
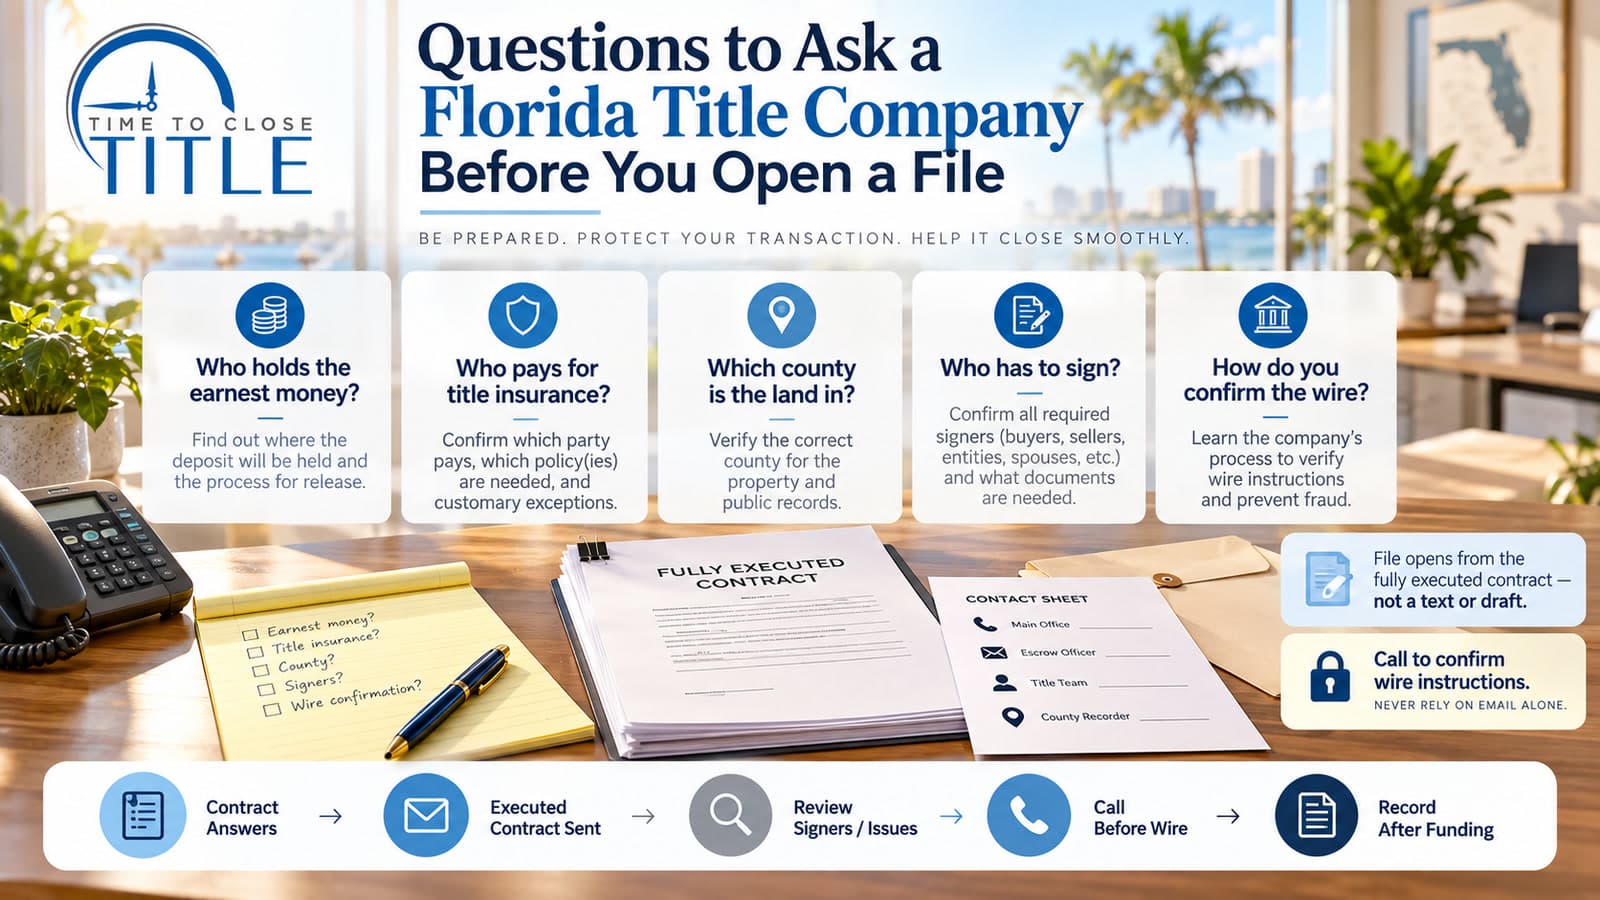
Ask who holds the deposit, who pays for title insurance, and how a wire is confirmed before the contract goes to title. A text that you are under contract does not open the file.

Title Insurance
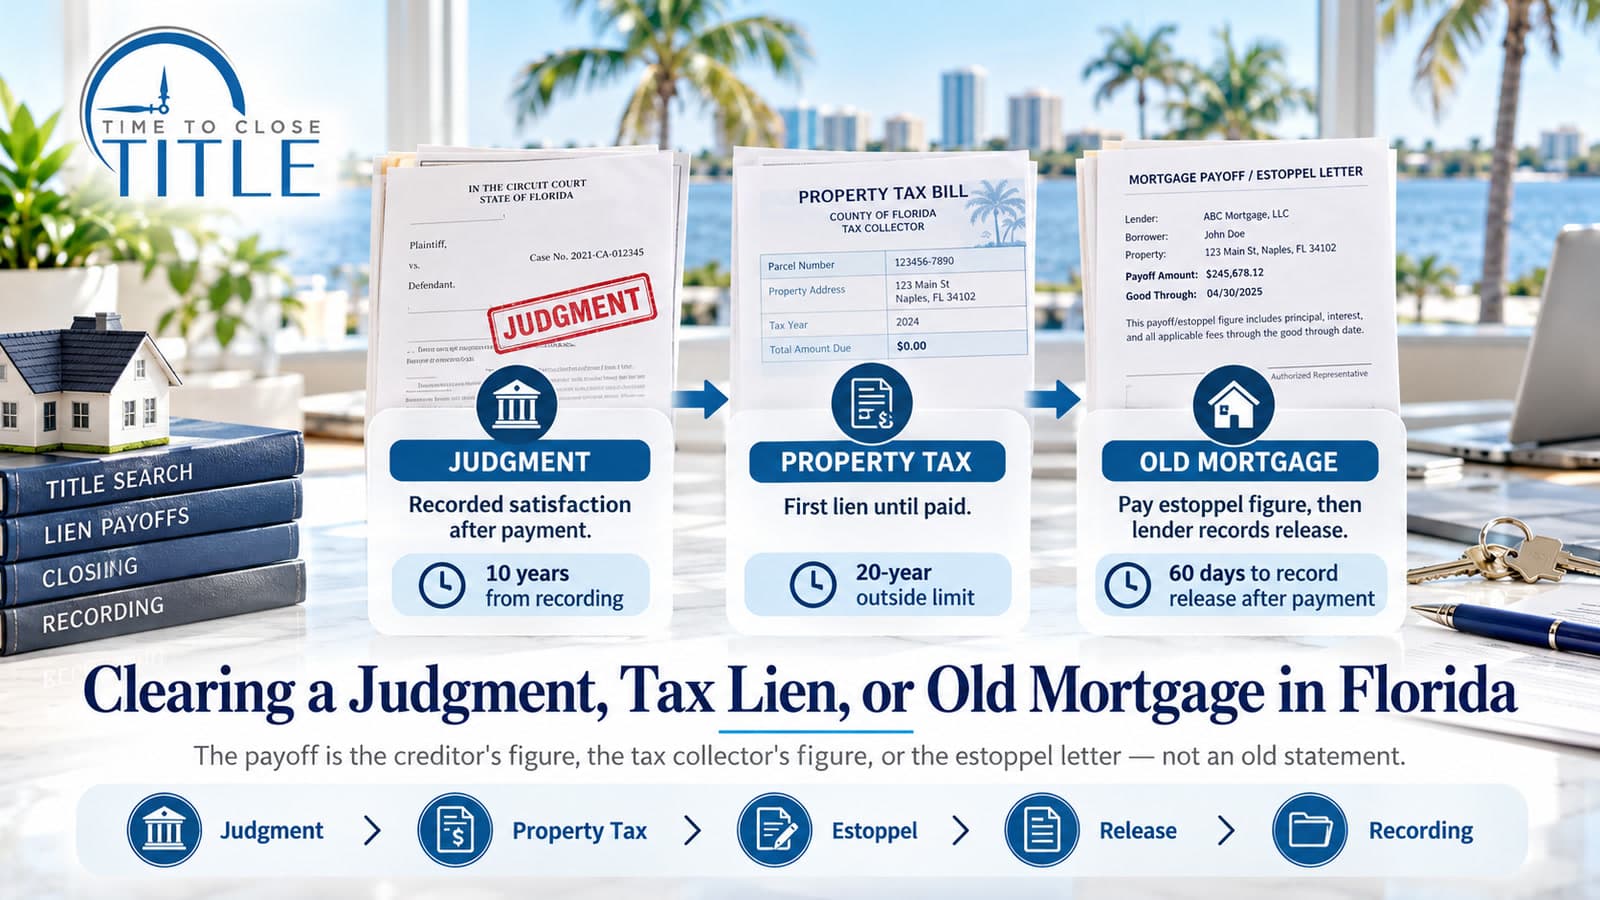
A judgment, unpaid property tax, or an old mortgage stays on the title until the creditor's figure is paid and the release is recorded. A coupon is not that figure.

Title Insurance
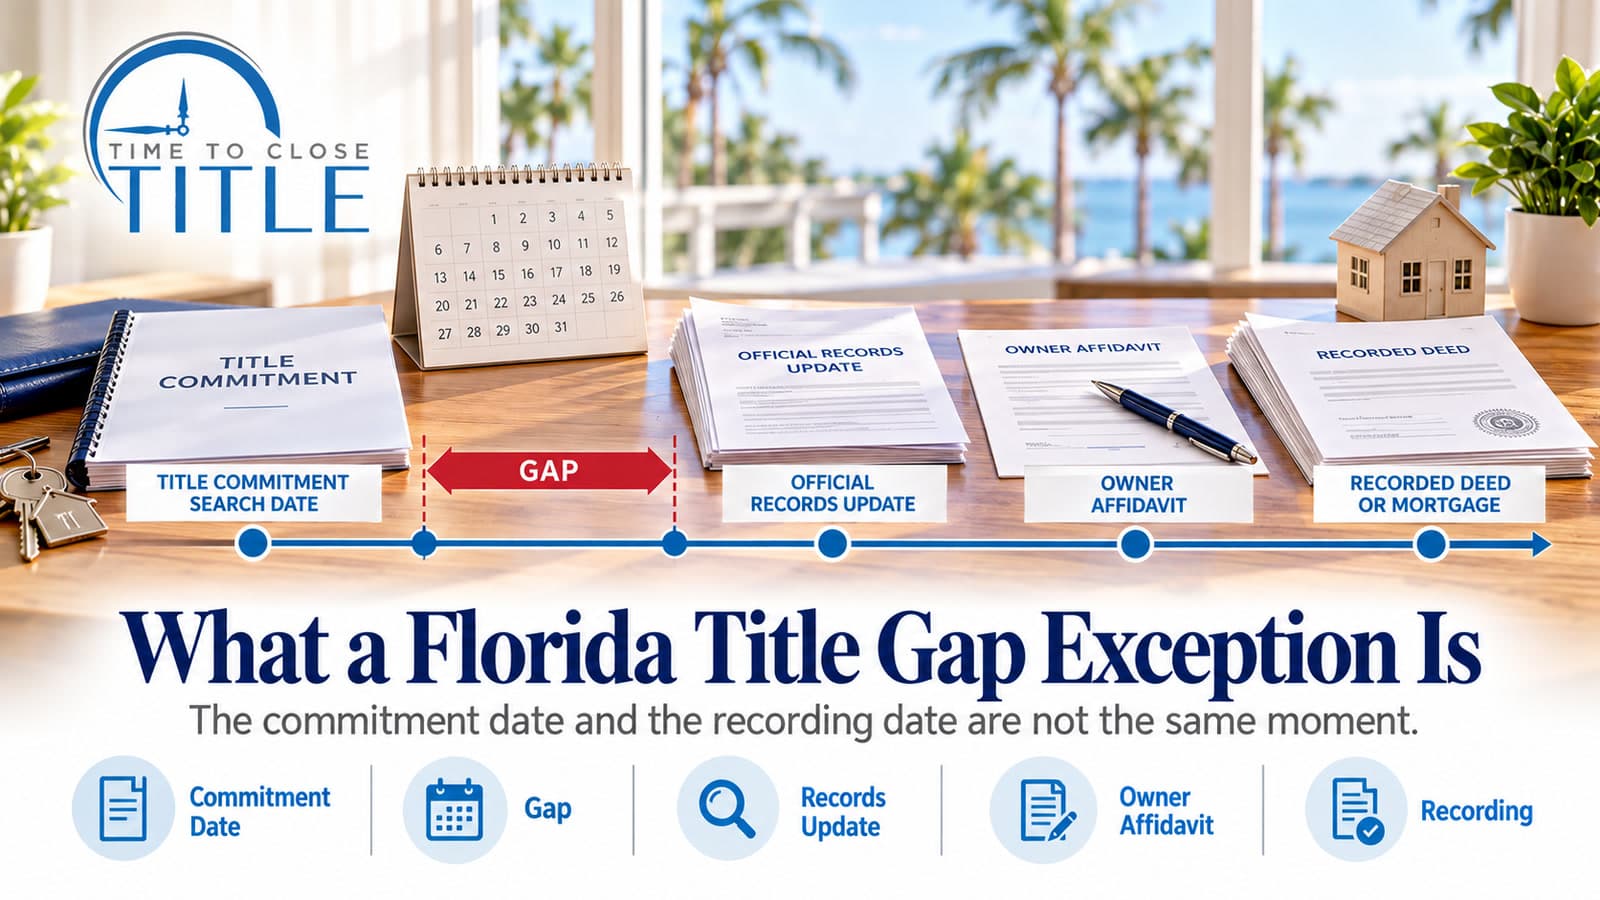
The title commitment stops on a search date. A lien recorded before the deed can still come first. Insuring the gap is what closes that hole.

The Closing Itself
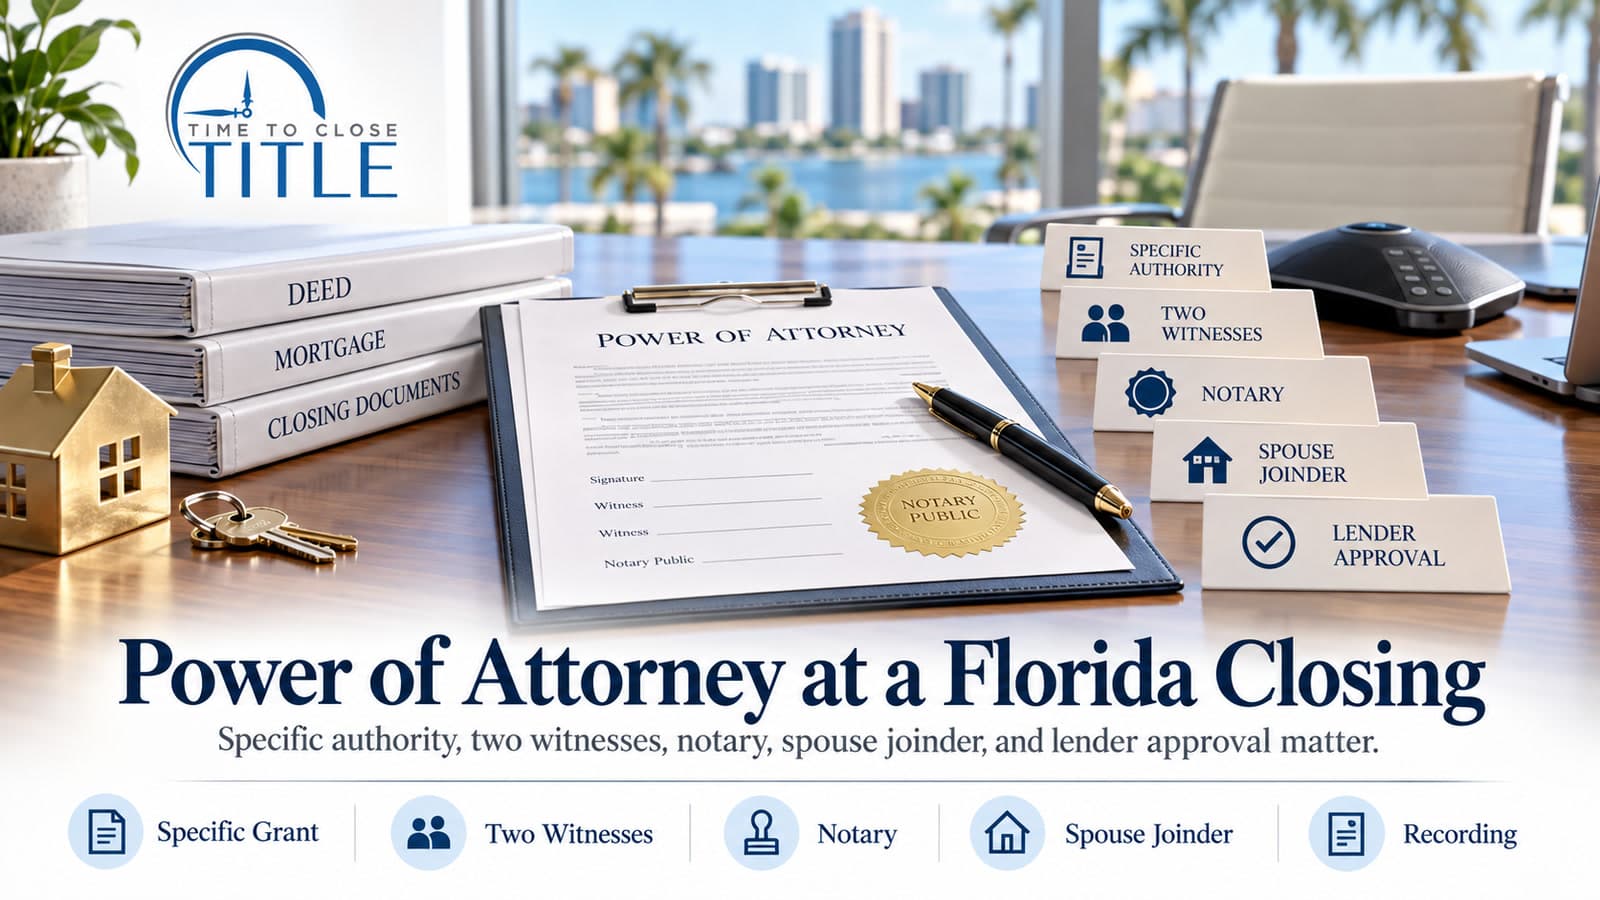
A power of attorney can sign a Florida deed only when it specifically grants that authority. A form that starts later, or after death, will not close the file.

The Closing Itself
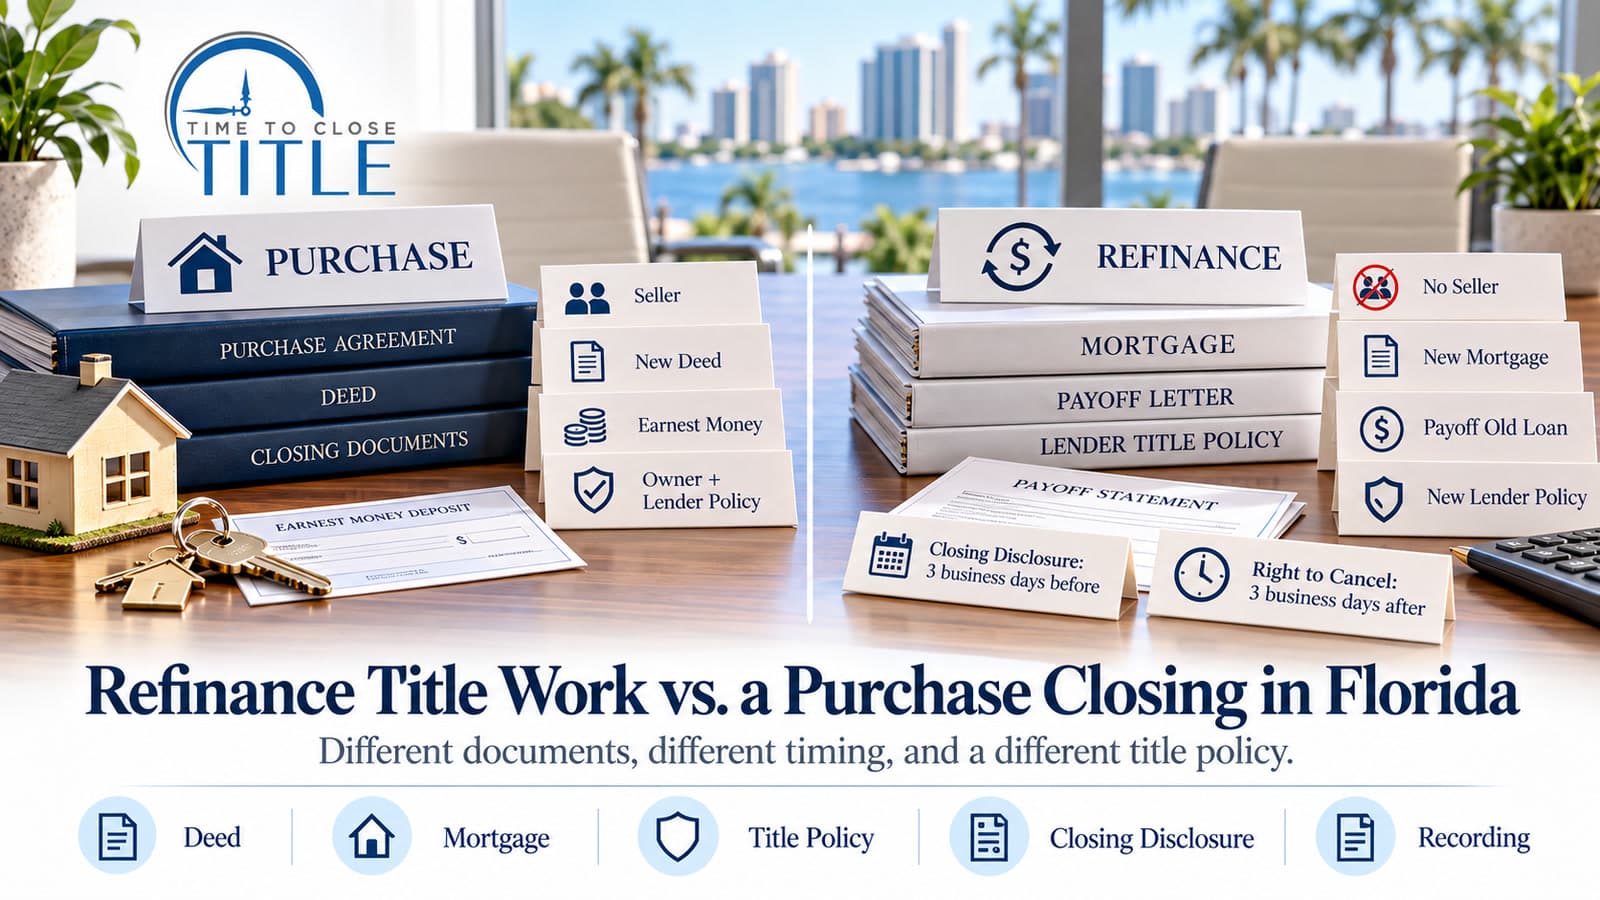
A refinance has no seller and usually no new deed. The new lender still needs a new title policy, and funding can wait for a right to cancel.

The Closing Itself
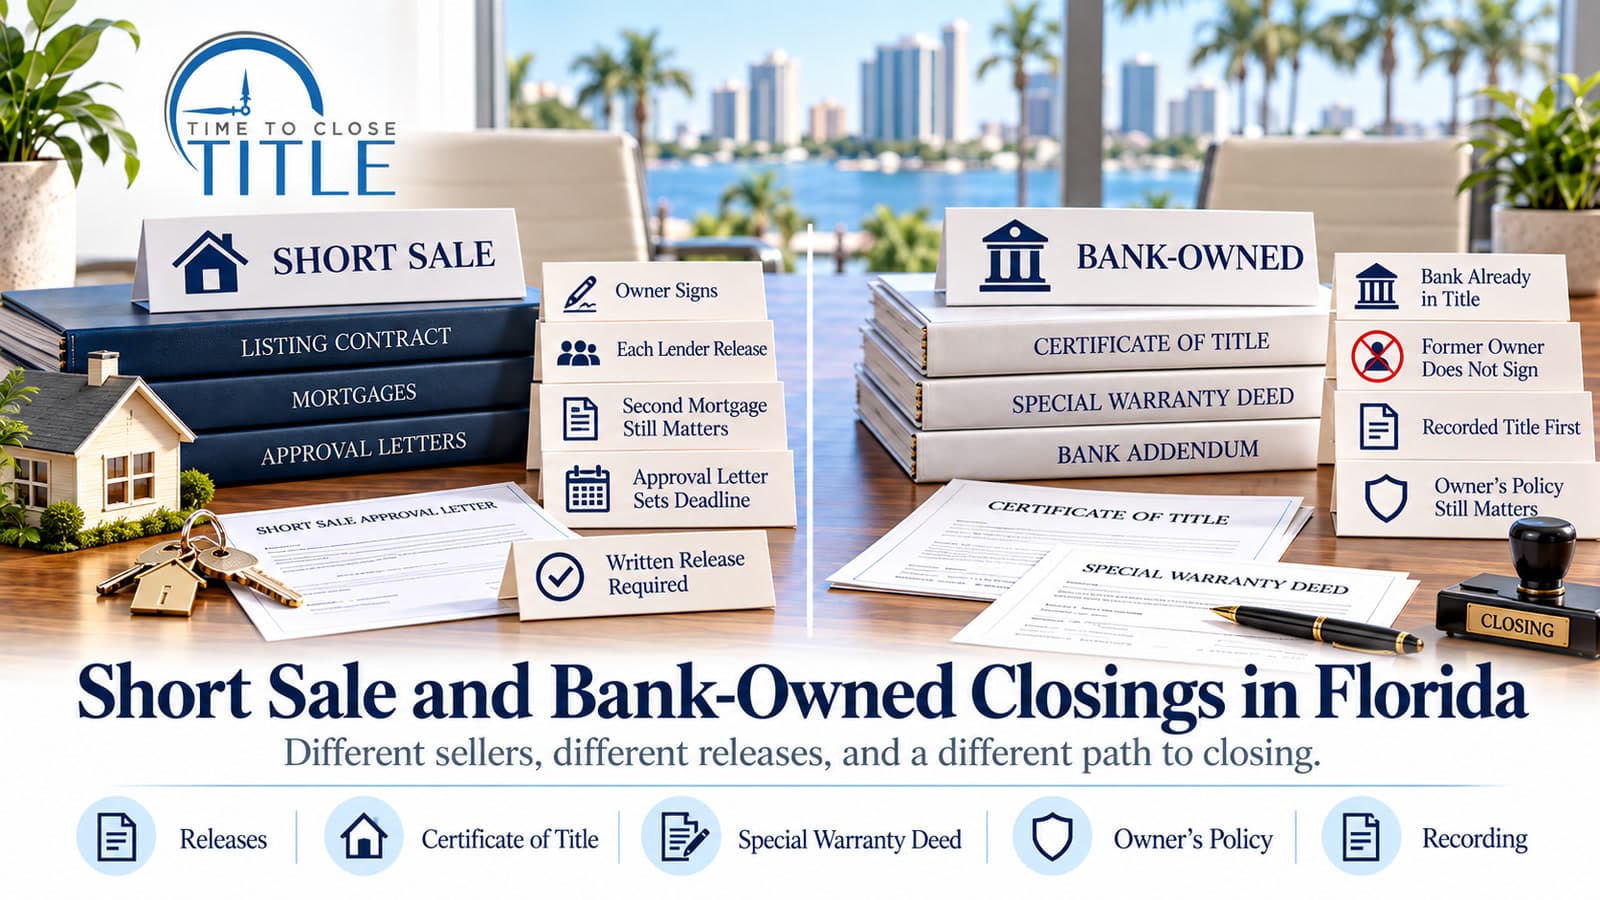
A short sale is the owner's sale, with each lender's written release. A bank-owned sale is the bank's sale, after the bank is already in title.

The Closing Itself
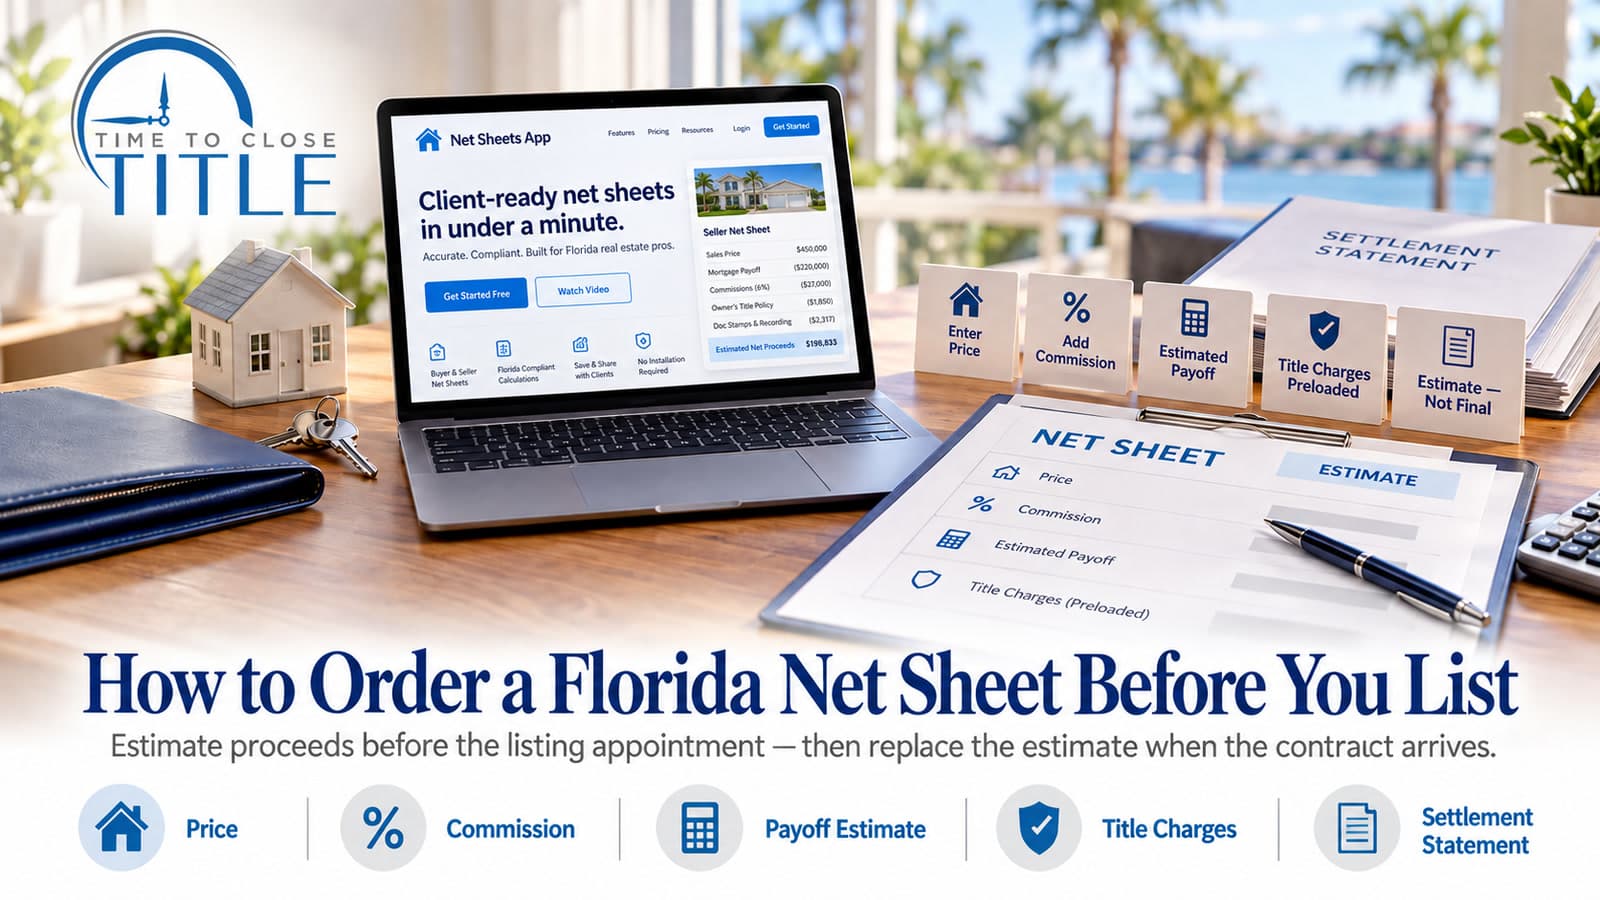
Order the estimate before the listing appointment. Title rates can be preloaded. The payoff, the commission, and the contract still have to come from you.

The Closing Itself
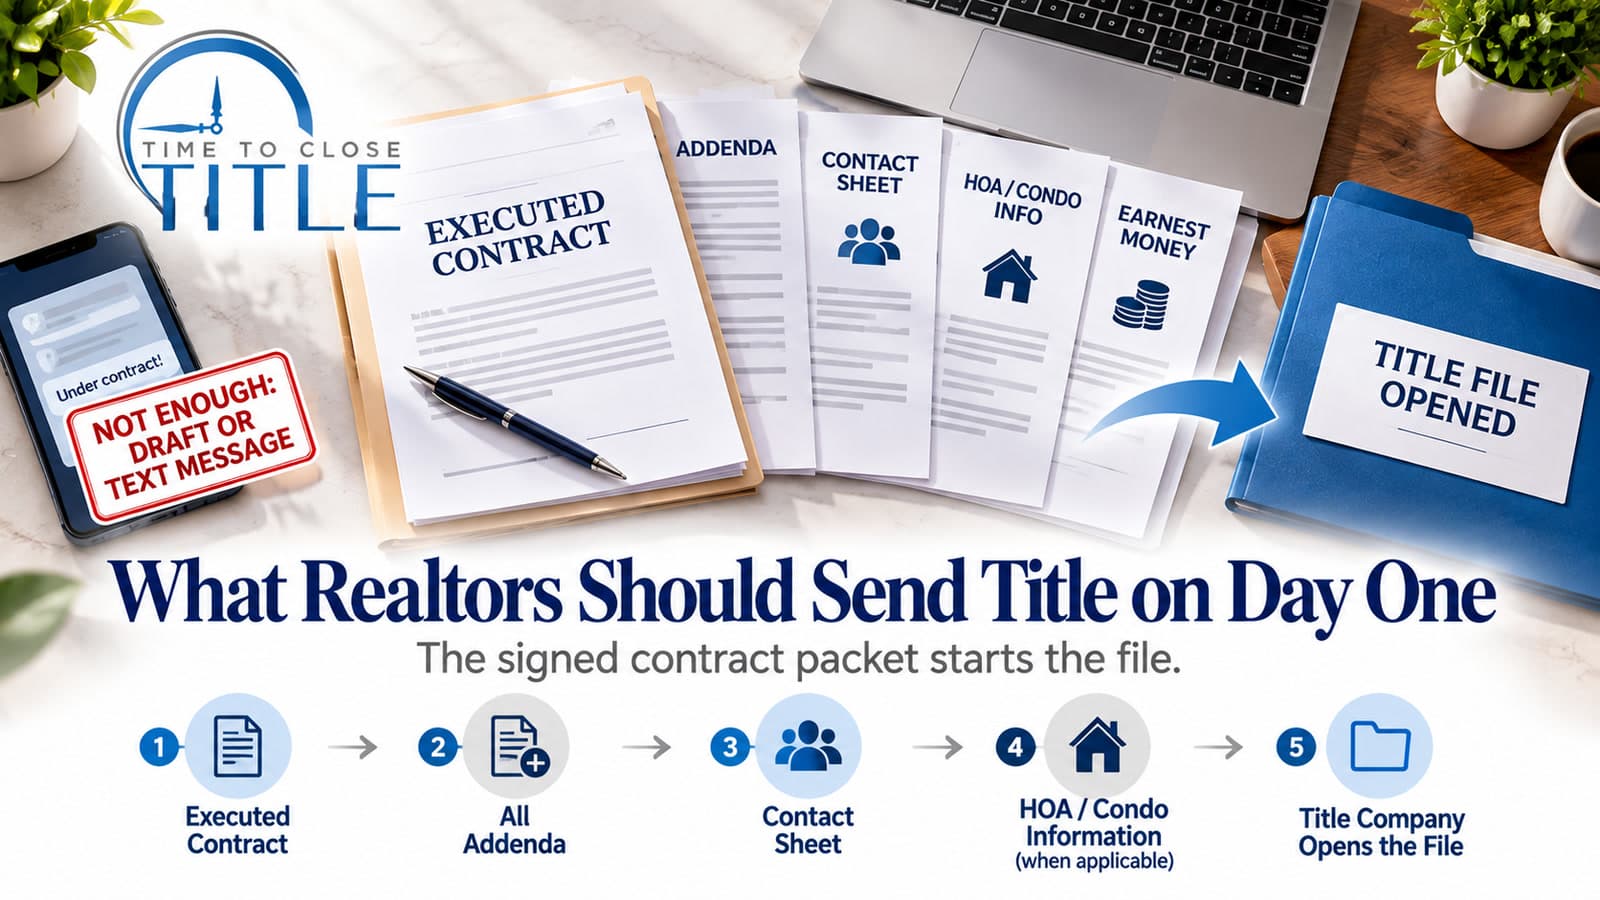
The file opens when the fully executed contract arrives, with a contact sheet and the association manager. A text that you are under contract is not the file.

The Closing Itself
A seller keeps the date by sending the loan, the association contact, and every signer with the contract. Packing day is too late for a payoff.

Closing Guides
A first Florida purchase uses the same closing path as any other purchase. The contract opens the file. Keys follow funding.

The Closing Itself
A rental and a homestead close on the same kind of deed. The spouse, the tax cap, and the tenant's deposit do not follow the same rules.

The Closing Itself
You can sign the deed from another state. You do not get the proceeds until the sale is funded, and every person on the title still has to sign.

The Closing Itself
You can close on a Florida house while you live somewhere else. The deed, the tax reset, and the wire instructions are what out-of-state buyers miss.

The Closing Itself
A house file has a calendar. A vacant tract waits on the legal description, a survey, and a recorded way in. A path people drive is not that way.

The Closing Itself
The house can take months. The title file still needs the certificate of occupancy, the notice of commencement, and proof the lienors were paid.

The Closing Itself
The association has 10 business days after it receives the request. The certificate, not a guess, is what we collect at closing.

The Closing Itself
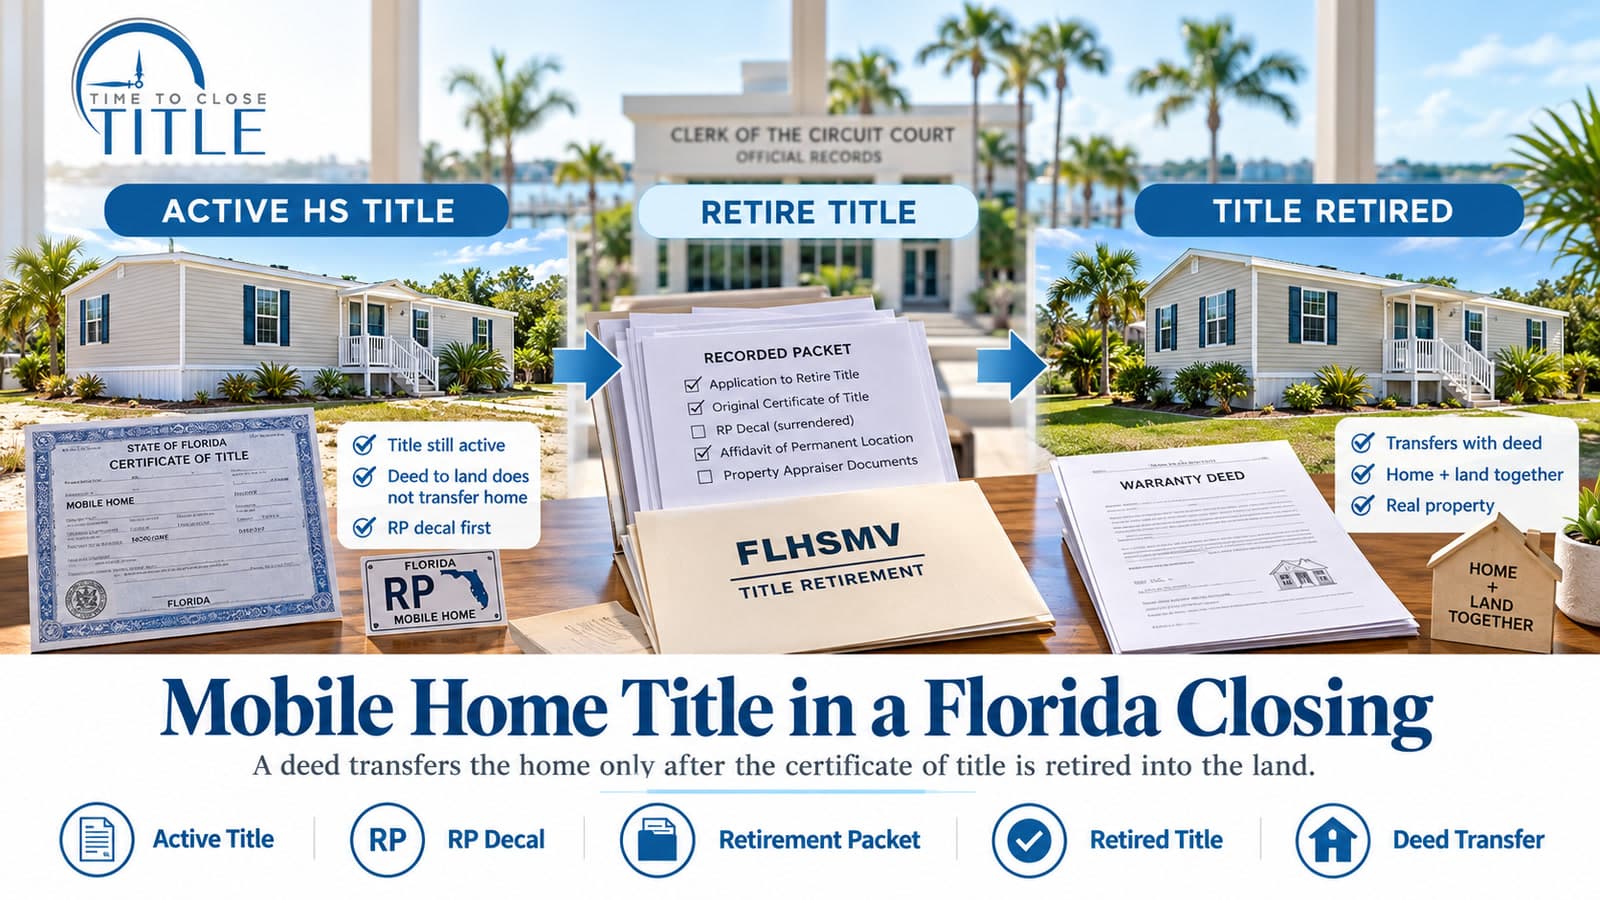
A deed transfers a Florida mobile home only after the certificate of title is retired. Until then, the home is still personal property.

Local Closings
You can sign in Spring Hill. The deed still goes to the clerk for the county where the land sits. Pasco and Citrus are not Hernando recording.

Local Guides
The Spring Hill office prepares the file. The clerk who records it is the clerk of the county where the land sits, and that is not always the same building.

Deed Guides
The heirs can agree and the will can name them. Official Records still need a deed from someone the court has authorized. That is the file a title company can insure.

Deed Guides
A form from another state will not put a Florida house in a beneficiary’s name at death. Florida never adopted a transfer-on-death deed. The recorded tools people use instead are a Lady Bird deed or a deed into a trust.

Deed Guides
Documentary stamp tax is a state tax on the deed, figured on consideration. A gift is not automatically free of it, and the clerk’s recording fee is a different charge.

Deed Guides
A misspelled name or a bad legal description does not age out of the official records. A new corrective deed restates the old transfer and fixes the error so the next search can read a clean chain.

Deed Guides
If the house is homestead, Florida generally requires the spouse to join a deed or mortgage even when only one name is on the last recorded deed. Skipping that signature is how a later sale or refinance finds a defect.

Deed Guides
A Lady Bird deed is Florida’s enhanced life estate deed. You keep the right to sell or mortgage. The remainderman takes title at death if the deed is still in place. That is not a trust and not a gift of the house today.

Deed Guides
The trust papers do not rewrite Official Records. A new deed to the trustee is what puts the house in the trust. The mortgage does not change with that deed.

Deed Guides
A divorce judgment can award the house. Official Records still need a new deed. Removing a name does not take that person off the mortgage.

Deed Guides
You cannot edit the old deed. A new recorded deed puts a spouse on title. Homestead often requires both spouses to join, and the loan does not change with the deed.

Title Insurance
The deed history and the city or utility counter are two different searches. An unpaid water or code lien can hold a closing just as firmly as an unreleased mortgage.

The Closing Itself
The settlement statement is the math of the file. One column is what you owe. The other is what you get credit for. They have to balance before anyone is paid.

Title Insurance
Enhanced owner's coverage is a broader title form, not a homeowner's insurance policy. It is available on some 1–4 family homes and still will not rebuild the roof.

The Closing Itself
Signing is not funding. If the wire or the lender has not come in, the seller is not paid and the keys usually stay put.

The Closing Itself
Cash removes the lender, the note, and the Closing Disclosure wait. The search, the settlement statement, and the recorded deed stay on the file.

The Closing Itself
FHFA opened VantageScore 4.0 to all approved GSE lenders. Title premiums and the search do not change. Lender conditions and clear-to-close timing might.

Title Insurance
A title claim asks the insurer to defend or pay a covered ownership defect. It is not a homeowner's claim, and exceptions on Schedule B are already outside the policy.

The Closing Itself
Most missed dates are open items that sat too long — payoffs, HOA letters, municipal charges, surveys, and last-minute loan conditions.

Title Insurance
Paying cash does not skip the title search. It just means the only policy that can protect you is the one you choose to buy.

The Closing Itself
The deed and the mortgage have to hit the Official Records. Until they do, later buyers and examiners may not see the transfer.

The Closing Itself
The Closing Disclosure is the lender's three-day numbers document on a financed purchase. Title supplies figures. Cash files use a settlement statement instead.

The Closing Itself
The title company holds the deposit and the closing wires until the contract and a balanced statement allow a release. Email from one side is not enough.

The Closing Itself
Someone with authority has to sign. That can be in our Spring Hill office, with a mobile notary, or by remote online notarization when the lender and the documents allow it.

Title Insurance
An old lender's policy cannot cover a new loan. Your owner's policy can stay in force, and a copy of it may unlock Florida's lower refinance title rates.

Title Insurance
A Florida title policy insures ownership, not the physical house. Here is what it leaves out, and how that differs from homeowner's and flood coverage.

Title Insurance
A Florida title search is a records exam, not a walkthrough. Here is what it finds in the chain of title, and why municipal liens matter as much as the deed history.

Title Insurance
Florida custom often has the seller pay the owner's policy and the buyer pay the lender's policy. The purchase contract, not the custom, is what actually controls.

Title Insurance
The lender's policy protects the bank. The owner's policy protects you. Here is the difference, the cost of skipping owner's coverage, and when to buy both.

Local Guides
A Hernando County closing uses the same Florida timeline, with local taxes, utilities, HOAs, and recording at the Brooksville clerk.

Closing Guides
A week-by-week Florida closing timeline, plus the delays that push dates and the steps buyers can take to close on time.

Title Insurance
Florida title insurance premiums are regulated. Here is how the rate is calculated, what a typical owner's policy costs, and which closing fees are separate.

Deed Guides
A complete Florida guide to quitclaim deeds, also searched as quick claim deeds: what they do, when to use them, taxes, recording, and title risks.

Deed Guides
The deed type decides how much protection the new owner gets. Here is when Florida uses a warranty deed, a special warranty deed, or a quitclaim.

Title Insurance
A plain-language guide to Florida title insurance: what it covers, what it costs, and whether buyers should purchase an owner's policy.

Closing Guides
A practical buyer and seller checklist for Florida closing day: identification, funds, documents, and the items that actually delay signing.

Closing Guides
Florida closing wire fraud is a callback problem, not a technology problem. Here is how the scam works and how to send funds safely.